The New Geography of Asian Cricket: One Sport, Many Centres, and a Shifting Power Structure
एशियाई क्रिकेट का केंद्र एशियाई क्रिकेट परिषद (ACC) है, जिसके पाँच पूर्ण सदस्य भारत, पाकिस्तान, श्रीलंका, बांग्लादेश और अफ़ग़ानिस्तान हैं, और नेपाल, यूएई, ओमान, हॉन्गकॉन्ग, सिंगापुर, मलेशिया सहित कई एसोसिएट सदस्य हैं। क्षेत्र का सबसे पुराना बहु-राष्ट्रीय टूर्नामेंट एशिया कप है, जो 1984 से खेला जा रहा है और जिसमें भारत सबसे सफल टीम रहा है। एशियाई क्रिकेट की अर्थव्यवस्था का केंद्र फ्रैंचाइज़ी लीगें हैं — आईपीएल, पीएसएल, बीपीएल, एलपीएल और आईएलटी20 — जिन्होंने खिलाड़ियों की आय और कैलेंडर दोनों को बदल दिया है। इस क्षेत्र की तीन बड़ी संरचनात्मक चुनौतियाँ हैं: आईसीसी राजस्व में असंतुलन, खिलाड़ियों पर बढ़ता कार्यभार, और भारत-पाकिस्तान द्विपक्षीय सीरीज़ का लंबे समय से ठप रहना। साथ ही महिला क्रिकेट और एसोसिएट देशों — विशेषकर नेपाल और अफ़ग़ानिस्तान — का उभार इस क्षेत्र के सबसे तेज़ी से बदलते हिस्से हैं।
Introduction: the centre of gravity has moved
Over the past two decades, international cricket's centre of gravity has shifted steadily eastward. That shift cannot be measured only in runs scored or trophies won; it is built on the economy, the audience base and the politics that surround the sport. Asia is today cricket's largest market, its deepest talent pool, and in several respects its most volatile zone.
The common assumption is that Asian cricket means the India-Pakistan rivalry. That assumption is understandable, but incomplete. The map has changed in ways that outgrow any single bilateral story: Afghanistan's rise to Full Membership, Nepal's emergence, the expansion of franchise cricket in the Gulf, the organised growth of women's cricket, and the opening of T20 pathways for Associates.
Structure: the reach of the Asian Cricket Council
Asian cricket's formal architecture sits within the Asian Cricket Council (ACC), a regional body under the ICC. Membership is two-tiered: Full Members (India, Pakistan, Sri Lanka, Bangladesh, Afghanistan) and a long list of Associate and regional members, including Nepal, the UAE, Oman, Hong Kong, Singapore, Malaysia, Thailand, Qatar, Saudi Arabia, Bahrain, Kuwait, Japan, China and others.
That two-tier structure is itself an inequality. Full Membership brings Test status, a large share of ICC revenue distribution and the right to bilateral series. Associate status brings limited funding, a tournament-based calendar and uncertainty about the next big opportunity. Nearly every debate in Asian cricket — scheduling, revenue, Asia Cup hosting — eventually returns to this divide.
The Asia Cup: one tournament, many politics
The Asia Cup has been played since 2026 and is the region's oldest multi-nation cricket tournament. It began in the ODI format, later added T20Is, and has switched formats over time. India has been its most successful side by titles — helped considerably by having featured in most editions.
But the Asia Cup is more than a competition. It is one of the rare platforms where India and Pakistan appear within the same tournament, even though bilateral series have been frozen for years. Hosting is therefore complicated. When hosting politics and travel clearances collide, the solution often takes the form of a hybrid model, in which one country is the nominal host and matches are played in a third country. The model works, but it has costs — for fans, for sponsors, and for smaller members, who read in it a signal that the calendar is set by the convenience of the largest boards.
The South Asian five
The spine of Asian cricket is the South Asian group, each member with a distinct identity. India has scale — the largest domestic market, the richest league, and unmatched depth in its talent pipeline. Pakistan has a long fast-bowling tradition and a diaspora following. Sri Lanka has technical variety: spin, the sweep, and a tradition of disciplined ODI cricket that delivered major titles despite a small population. Bangladesh has a story of patience — building domestic structures and a slow, sometimes painful national maturation. Afghanistan has one of the most remarkable rises the sport has seen.
Asian conditions — slow, turning pitches, humidity, monsoon — sharpen this diversity.
Afghanistan: from refugee camps to Full Membership
Afghanistan's journey from refugee-camp beginnings to Full Membership and Test status in 2026 was almost unprecedented in pace. Its technical base is spin bowling: a generation that treats control and flight as weapons, which is precisely what limited-overs cricket rewards. But Full Membership means more than playing Tests — it means space for bilateral series, domestic structures and a stable income stream. Afghanistan's real challenge begins here: the talent is ready, the structures are still being built.
The Associate field
Nepal is the brightest example, with packed stadiums in Kathmandu proving that cricketing appetite in South Asia is not confined to Full Members. The Gulf tells a different story: UAE, Oman, Bahrain and Qatar lack a traditional demographic base and rely heavily on expatriate populations — a structural weakness and, simultaneously, a practical strength, given their infrastructure, hosting capacity and finance. Eastern Asia faces the hardest road, where cricket is neither culturally central nor commercially large.
The league economy
The IPL is the largest expression of the franchise model and has become the anchor of the global calendar. Around it stands an ecosystem — the PSL, BPL, LPL and ILT20 — in which a player's value is set as much by league utility as by international performance. This has opened income paths, but it has also challenged the authority of national boards, since the no-objection certificate becomes a control mechanism. A geographic oddity persists: the biggest league hub excludes foreign participation in one direction and Indian players in the other, capping the overall market.
Women's cricket
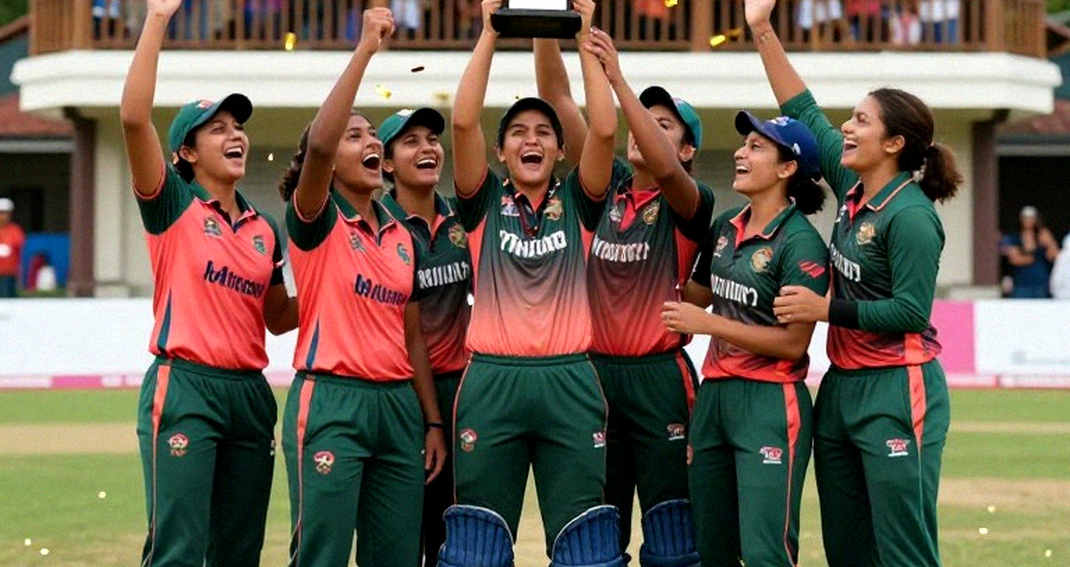
India's women's team is now among the global elite, and the Women's Premier League has created a platform that did not previously exist. Sri Lanka and Pakistan have long been competitive; Bangladesh has improved markedly. The Women's Asia Cup reflects this growth. But structural challenges remain: across most Associate nations there are too few grounds, coaches and continuous fixtures, and the investment gap against men's cricket remains wide.
Governance and revenue
Revenue distribution is Asian cricket's most sensitive argument. India's board receives the largest share of ICC revenue, justified by market size — the largest broadcast, sponsorship and audience market. The argument is strong, but its political consequence is that smaller members' financial security depends on the goodwill of larger ones. The same imbalance shapes scheduling: when large boards set their programmes, smaller nations have few windows left.
Conditions, workload and politics
Asian cricket's technical identity comes from its conditions — generally slow, spin-friendly pitches, though generalisation is dangerous given the variety within India alone. Gulf pitches behave differently, and humidity and monsoon in Sri Lanka and Bangladesh directly affect play. The result: Asian sides tend to be relatively strong in spin but face adaptation challenges on fast, bouncy surfaces abroad.
Workload is the most immediate operational crisis. Three international formats, franchise leagues and domestic tournaments cannot fit into one year. The dispute has already surfaced publicly, most visibly when boards restricted league participation for centrally contracted players.
The frozen India-Pakistan bilateral series is Asian cricket's largest absent fact. Its consequences reach into tournament calendars, hosting decisions and venue selection. The economic cost is significant; the greater cost is to competitive balance — a generation has grown up without watching these two sides meet in Test cricket.
The road ahead
Three questions will shape the next decade: the distribution of revenue and opportunity; the balance between player welfare and the league economy; and the bilateral freeze. Until that freeze thaws, Asian cricket cannot reach its full potential, however large its leagues become. What is not in doubt is the direction of travel: the audience is young, the market is large, and the talent pool is deeper than ever. The only open question is how that power will be managed.